Budgeting Smartly for Long-Term Education Costs
July 9, 2026 2026-07-06 14:27Budgeting Smartly for Long-Term Education Costs
Budgeting Smartly for Long-Term Education Costs
Introduction
Managing the cost of education is a long-term project that benefits from clear priorities and steady planning. Early assessment and realistic expectations make it easier to balance savings, aid, and personal contributions. Families and learners who create flexible plans can adapt to changing circumstances without derailing goals. This article outlines practical steps to evaluate finances, choose funding strategies, and reduce expenses while keeping educational quality high.
Building a coherent approach means combining short-term actions with multi-year planning. The suggestions below aim to be practical and adaptable to different stages of a learner’s journey.
Assess your current financial position
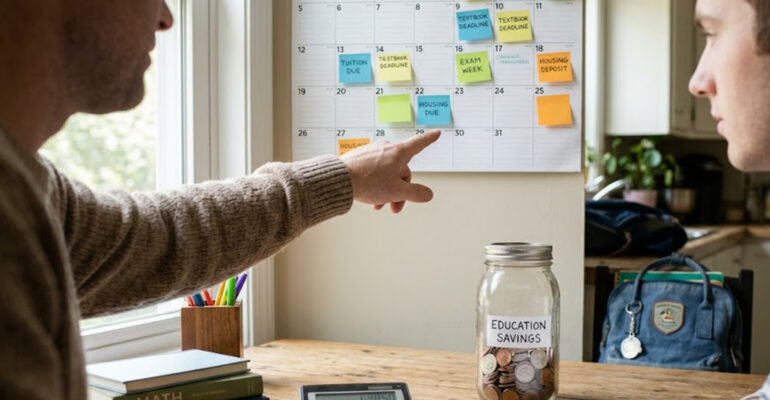
Begin by compiling a clear picture of income, regular expenses, existing savings, and any education-specific accounts. Include realistic estimates for tuition, fees, living costs, and materials so you avoid surprises later. Factor in inflation and likely changes to household earnings over time, and review tax-advantaged accounts or employer benefits that could offset costs. A written snapshot helps prioritize what to fund first and where to focus savings measures.
Regularly revisiting this assessment ensures the plan stays aligned with actual circumstances. Setting milestones and checkpoints makes it easier to measure progress and adjust contributions as needed.
Compare funding strategies and timelines
Different strategies suit different timelines and risk tolerances: short-term needs often rely on scholarships, grants, or current income, while long-term funding benefits from dedicated savings or investment accounts. Understand the trade-offs of loans versus savings, and weigh potential future earnings against current borrowing costs. When possible, combine multiple sources to reduce reliance on any single option and build redundancy into your approach. Timing matters—starting contributions earlier typically reduces monthly pressure later.
- Scholarships and grants: nonrepayable, merit or need-based.
- Savings accounts and tax-advantaged plans: predictable and controlled.
- Loans and income-share agreements: manage carefully to avoid oversizing debt.
- Work-study and part-time employment: provide cash flow and experience.
Mapping these options to likely timelines lets you create a phased plan that balances immediate affordability with long-term sustainability. Revisit choices as financial aid packages and personal circumstances evolve.
Practical ways to reduce education expenses
Reducing costs often requires a mix of behavioral changes and strategic choices, like choosing lower-cost programs for general education, using open educational resources, or buying used textbooks. Encouraging part-time work, internship opportunities, or employer tuition assistance can offset living expenses and enhance career prospects. Small recurring savings—cutting nonessential subscriptions or reallocating bonuses—add up over several years. Transparency and collaboration within families or learning partnerships help maintain commitment to the plan.
- Share housing and transportation to lower living costs.
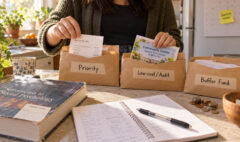
- Audit recurring expenses and redirect savings to education funds.
- Seek community resources, mentorships, and free learning tools.
Practical cost reductions protect both finances and learning outcomes when implemented thoughtfully. Combine savings tactics with reliable funding to preserve academic quality.
Conclusion
Careful assessment, diversified funding strategies, and practical cost reductions create a resilient approach to education expenses. Regular reviews and small adjustments keep plans realistic and achievable. With clear priorities and discipline, learners can pursue education without unnecessary financial strain.